

流动性、价格与资金池规则
TWAP and VWAP: averages answer different questions
Time weighting, volume weighting and executable liquidity should never be collapsed into one number.
文章正文和技术图表为英语,导航提供 7 种语言。
参考指南
Start with the weighting rule
A time-weighted average weights observations by duration; a volume-weighted average weights trades by the amount traded. A price that persists for a long interval can dominate a TWAP even with little trading. A brief period with heavy volume can dominate a VWAP. Before comparing either benchmark, identify the sampling method, window, market and denomination.
Not every on-chain TWAP is arithmetic
Uniswap v3 accumulates ticks over time. Deriving an average tick and converting it to a price yields a geometric time-weighted price, subject to the protocol’s tick representation and rounding. This is not the same calculation as averaging displayed dollar prices on a chart. Oracle observation history and the chosen lookback window determine what can be calculated. 1
An average is not depth
Neither statistic says how much can be sold now. A market can have a stable historical average and thin current liquidity. A VWAP can also reflect trading that is economically uninformative, including activity whose independence is uncertain. A TWAP smooths short-lived movement, but a long window can lag a genuine repricing. Weighting does not remove the need to inspect the underlying market.
Use the benchmark honestly
State whether you are measuring an execution, marking a portfolio or feeding a contract. A trading algorithm called TWAP describes an execution schedule, while a TWAP oracle describes a price measurement. The shared acronym does not make them interchangeable. Keep benchmark performance separate from trading costs, partial fills and the price at which an entire position could exit.
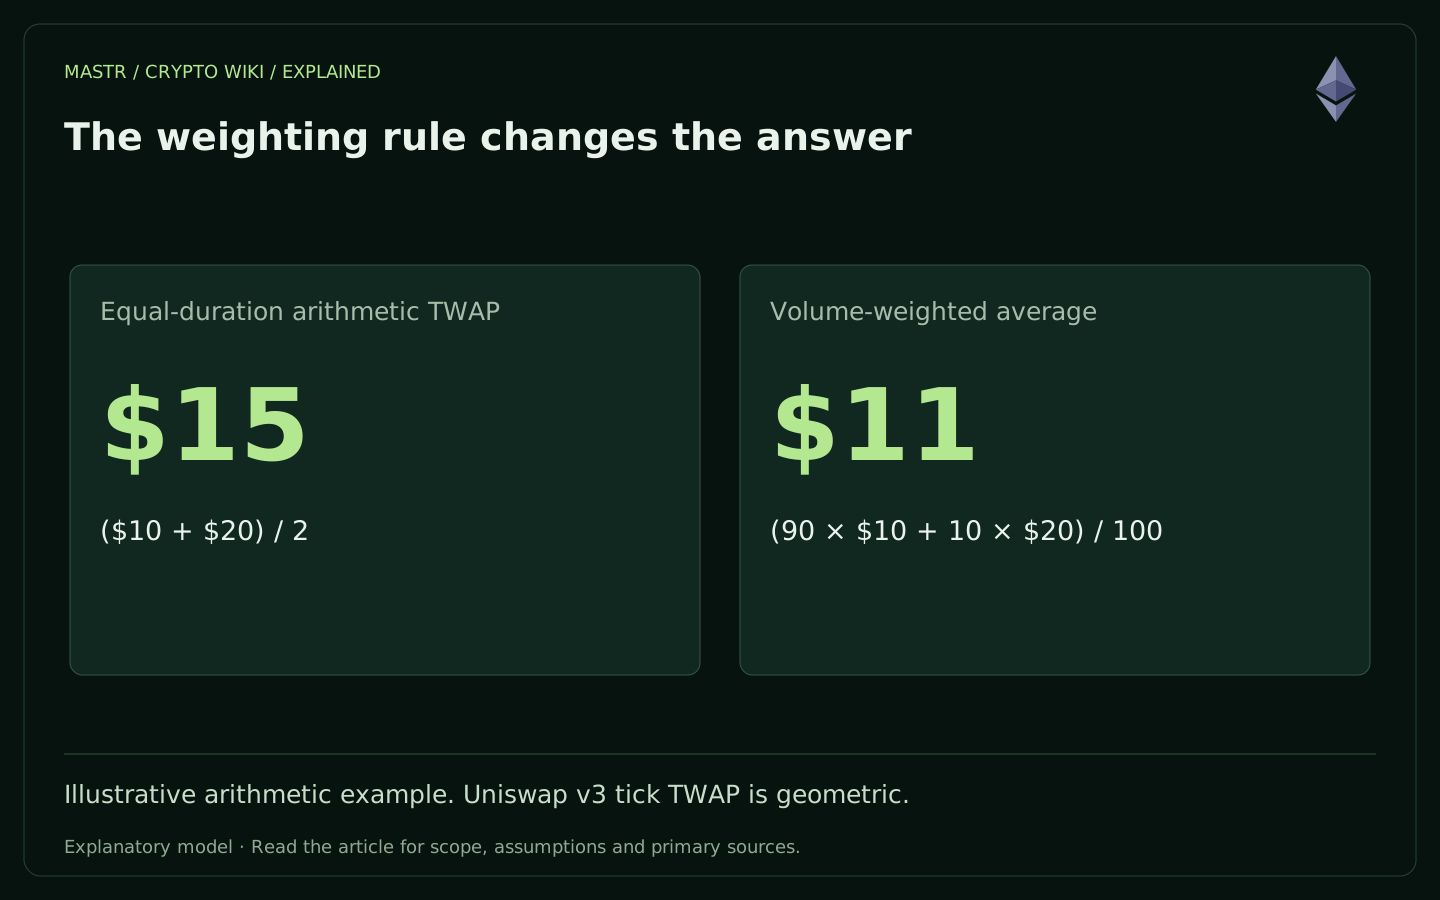
具体示例
For 2 equally long intervals priced at $10 and $20, the arithmetic TWAP is $15. If the traded volumes are 90 and 10 units, the VWAP is $11. Both calculations are correct for their stated inputs. Neither means a new 100-unit order can execute at that price.