

MASTR · CRYPTO & WEB3
Market cap versus the exit: a worked liquidity model
A marginal quote values the whole supply on paper. Selling a position changes the pool that produced that quote.
章节正文和技术图表为英文,导航支持七种语言。
How much can a holder actually receive when selling?
One price is being applied to many units
Market capitalisation usually multiplies a reported circulating supply by a current reference price. The result is a valuation measure, not a cash balance waiting for holders. The price may come from a small trade in a thin pool. If many holders try to sell, the trades change that price. Fully diluted valuation adds another assumption by applying it to a larger supply measure that may not yet be transferable.
A simple constant-product model
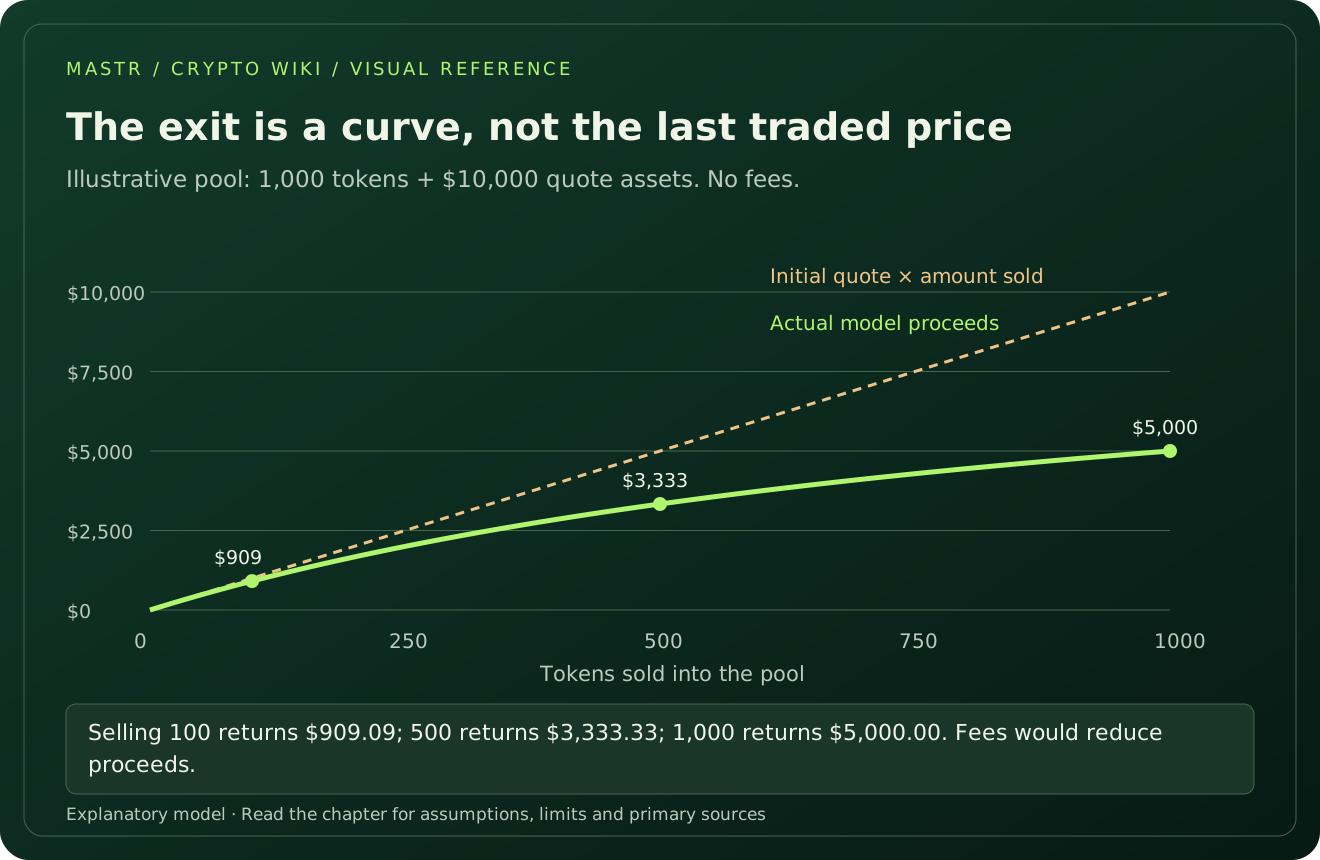
Consider an illustrative pool containing 1,000 tokens and 10,000 dollars of quote assets. Ignore fees and assume the simple invariant x times y equals 10,000,000. Its initial marginal price is 10 dollars per token. Sell 100 tokens into the pool: the new token reserve is 1,100 and the quote reserve becomes about 9,090.91. The seller receives about 909.09 dollars, an average of 9.09 per token. The initial quote would have suggested 1,000 dollars.
Price impact is built into the trade
After that sale, the new marginal price is about 8.26 dollars. The average execution price and the final marginal price are different. Fees would reduce proceeds further. Slippage tolerance is another concept: it limits how far actual execution may deviate from the expected quote under the transaction’s conditions. A large tolerance does not create liquidity; it permits a worse outcome.
Real markets add more structure
Concentrated liquidity is active only in selected price ranges. An aggregate TVL number may include assets outside the range a trade will use. Aggregators can split a trade across pools, but they cannot manufacture independent depth by displaying several routes through the same underlying liquidity. Order books have their own cancellations, priority rules and execution uncertainty. A pool snapshot is time-specific, not a standing guarantee.
Use a position-sized question
Instead of asking whether liquidity is high, ask for the expected proceeds from a specified sale at a specified state. Record route, fees, size and time. Consider how the outcome changes when other participants sell first or liquidity providers withdraw. A screenshot of a wallet value becomes more useful when accompanied by an executable-depth estimate and a clear explanation of the assumptions.
示例解析
In the same fee-free pool, selling 500 tokens returns about 3,333.33 dollars, not the 5,000 implied by the initial quote. Selling 1,000 returns 5,000 dollars, not 10,000. These are illustrative calculations, not live quotes, and the accompanying chart uses exactly this model.
思考问题
- Specify the position size.
- Report average proceeds, not just the last price.
- Do not treat TVL as immediately withdrawable cash.